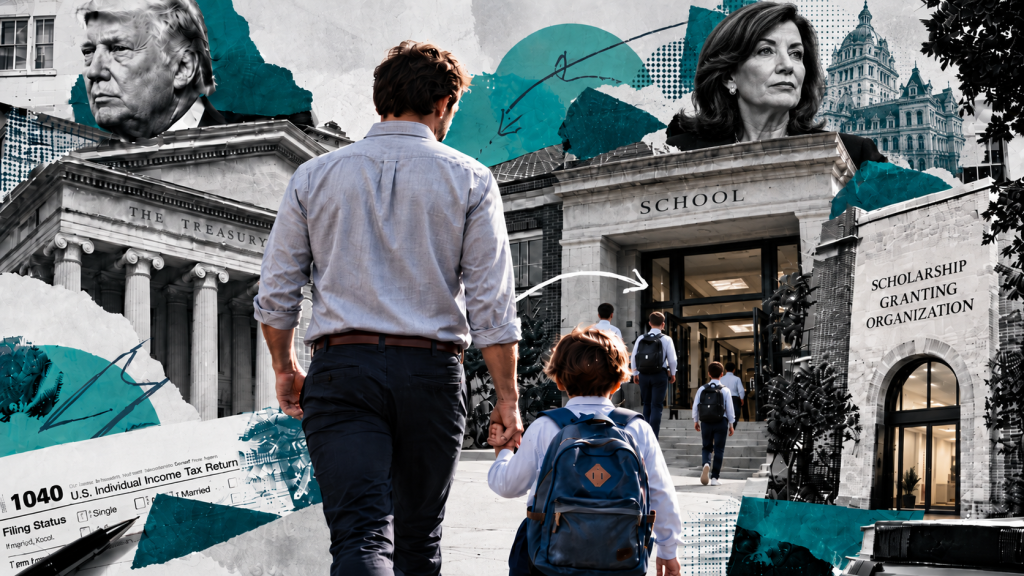
Treasury and the IRS released new federal scholarship tax-credit rules on October 1. Scholarship-granting organizations now have more detail on operating across state lines and the oversight that would come with participation.
Scholarship-granting organizations, or SGOs, are nonprofits that use donations to fund scholarships for eligible students’ K–12 education expenses. Donors may claim the federal tax credit for qualifying contributions to approved SGOs.
The regulatory package includes proposed operational rules and companion temporary rules for program administration. These are the top headlines for SGOs:
• An office in every participating state would not be required. An SGO could operate across state lines if it is authorized to do business in each state and complies with generally applicable charity laws.
• Participating states face limits on adding restrictions. States cannot narrow eligible school types or scholarship expenses beyond the federal requirements. They can still enforce charity laws and require documentation, reporting, and fraud controls tied to the program.
• Annual audits would cover finances and program operations. SGOs with total annual receipts above $500,000 would need an external independent auditor. Those with receipts of $500,000 or less could use a committee of independent persons unrelated to management.
• Some applicants could qualify without a separate full income check. A proposed safe harbor for students whose households receive certain government benefits could simplify eligibility review.
The comprehensive rules remain proposed and may change. Roth&Co will publish further analysis in the coming days to explain the practical implications for donors, families, and scholarship organizations.
This material has been prepared for informational purposes only, and is not intended to provide or be relied upon for legal or tax advice. If you have any specific legal or tax questions regarding this content or related issues, please consult with your professional legal or tax advisor.