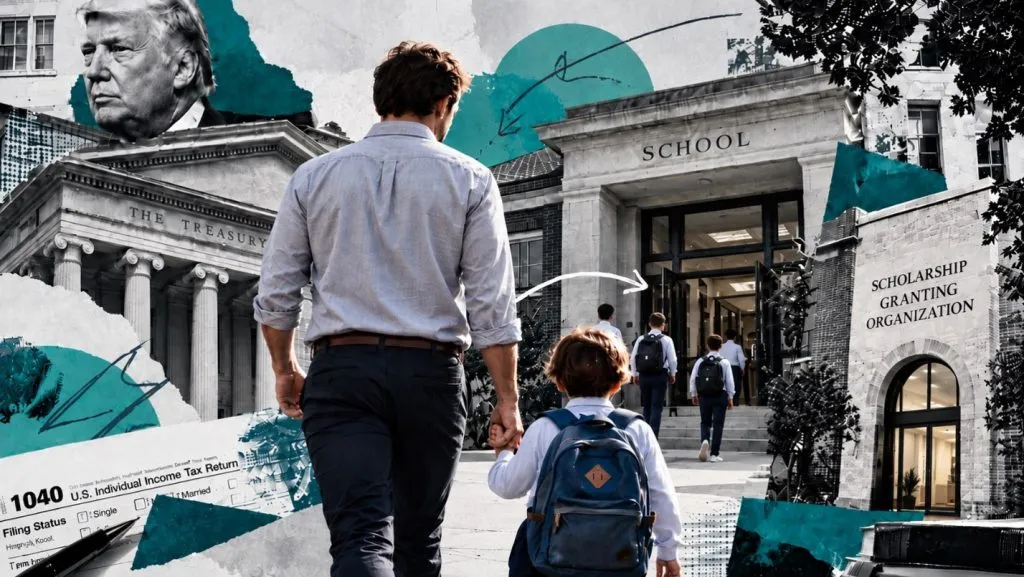
With tuition taking up so much of the family budget, parents are eager for the relief promised by the new federal education tax credit. However, getting that relief will be more roundabout than parents might expect. First, the money makes a pit stop at a Scholarship Granting Organization (SGO), which decides whose tuition bills it will help pay. Whether your family makes the cut for a scholarship is another question entirely.
The credit was created under President Trump’s One Big Beautiful Bill, signed into law in July 2025, and takes effect in 2027. An individual who donates to an approved Scholarship Granting Organization can receive a federal tax credit of up to $1,700 a year ($3,400 for a married couple). The credit reduces the donor’s federal income tax dollar for dollar, allowing someone with enough tax liability to recover the full amount of a qualifying donation up to that limit. Paying your own child’s tuition won’t qualify, so the immediate benefit is a cost-neutral donation.
After receiving the donations, the SGO pools the money and awards scholarships to eligible students. Since donors can’t earmark their contributions for any particular child, there’s no guarantee their own family will receive any money. But they can then apply for a scholarship, and the organization will decide who receives an award and how much they receive. Scholarships can be above or below $1,700, since that limit applies only to the donor’s tax credit.
Under the proposed rules, the SGO pays tuition scholarships directly to the school. The amount available for scholarships will depend on how much the SGO raises and how it distributes the money among applicants. Parents will also need to find out how their school handles an award alongside existing financial aid. If the school chooses to reduce its own assistance when an SGO scholarship comes in, the family may see less of a reduction in its tuition bill than the award suggests.
While SGOs can set their own scholarship criteria, they must first check that applicants meet the federal requirements. A student’s household income cannot exceed three times the median income for their area, adjusted for family size. Treasury estimates that roughly 95% of U.S. children fall below that income limit. However, the child must generally live in a participating state, and many states have not yet made the decision to participate.
For now, the SGO landscape is still taking shape. It’s too early to know how many organizations will participate or which families each will serve. Parents can start by urging their state leaders to opt in, opening the door to scholarships for their children.
This material has been prepared for informational purposes only, and is not intended to provide or be relied upon for legal or tax advice. If you have any specific legal or tax questions regarding this content or related issues, please consult with your professional legal or tax advisor.