A large capital gain brings both opportunity and exposure. Whether it comes from the sale of a business, real estate, or a concentrated stock position, federal rates, state taxes, and the net investment income tax can claim a substantial share of the proceeds. The decisions an investor makes around the timing of a sale and the reinvestment of the proceeds will determine how much of that gain is kept.
Two upcoming dates add a time element to those decisions. Gains deferred under the original Opportunity Zone rules generally come into income on December 31, 2026, and revised incentives will apply to qualifying investments made beginning January 1, 2027. Investors weighing a sale, or a reinvestment, are working against both dates.
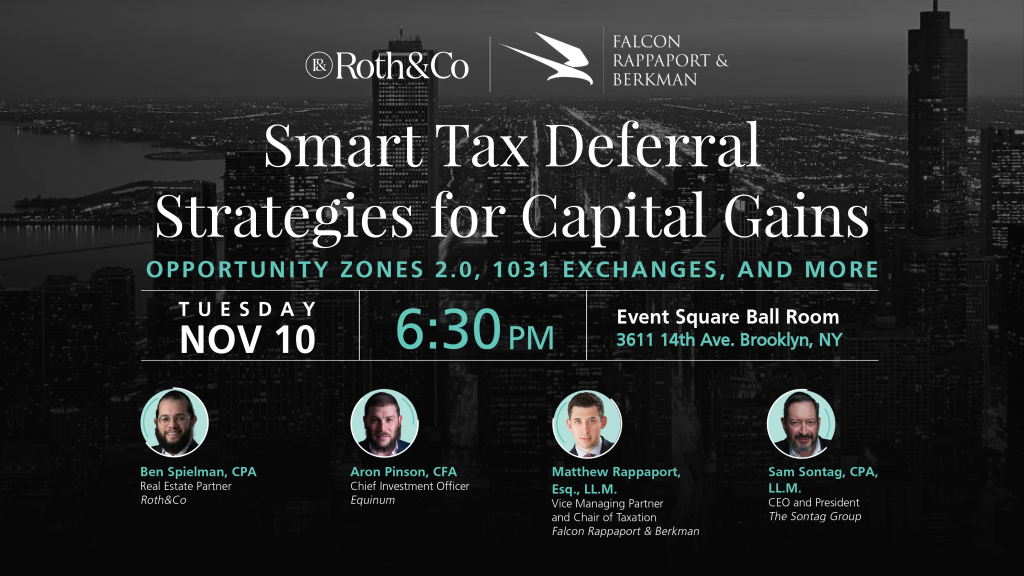
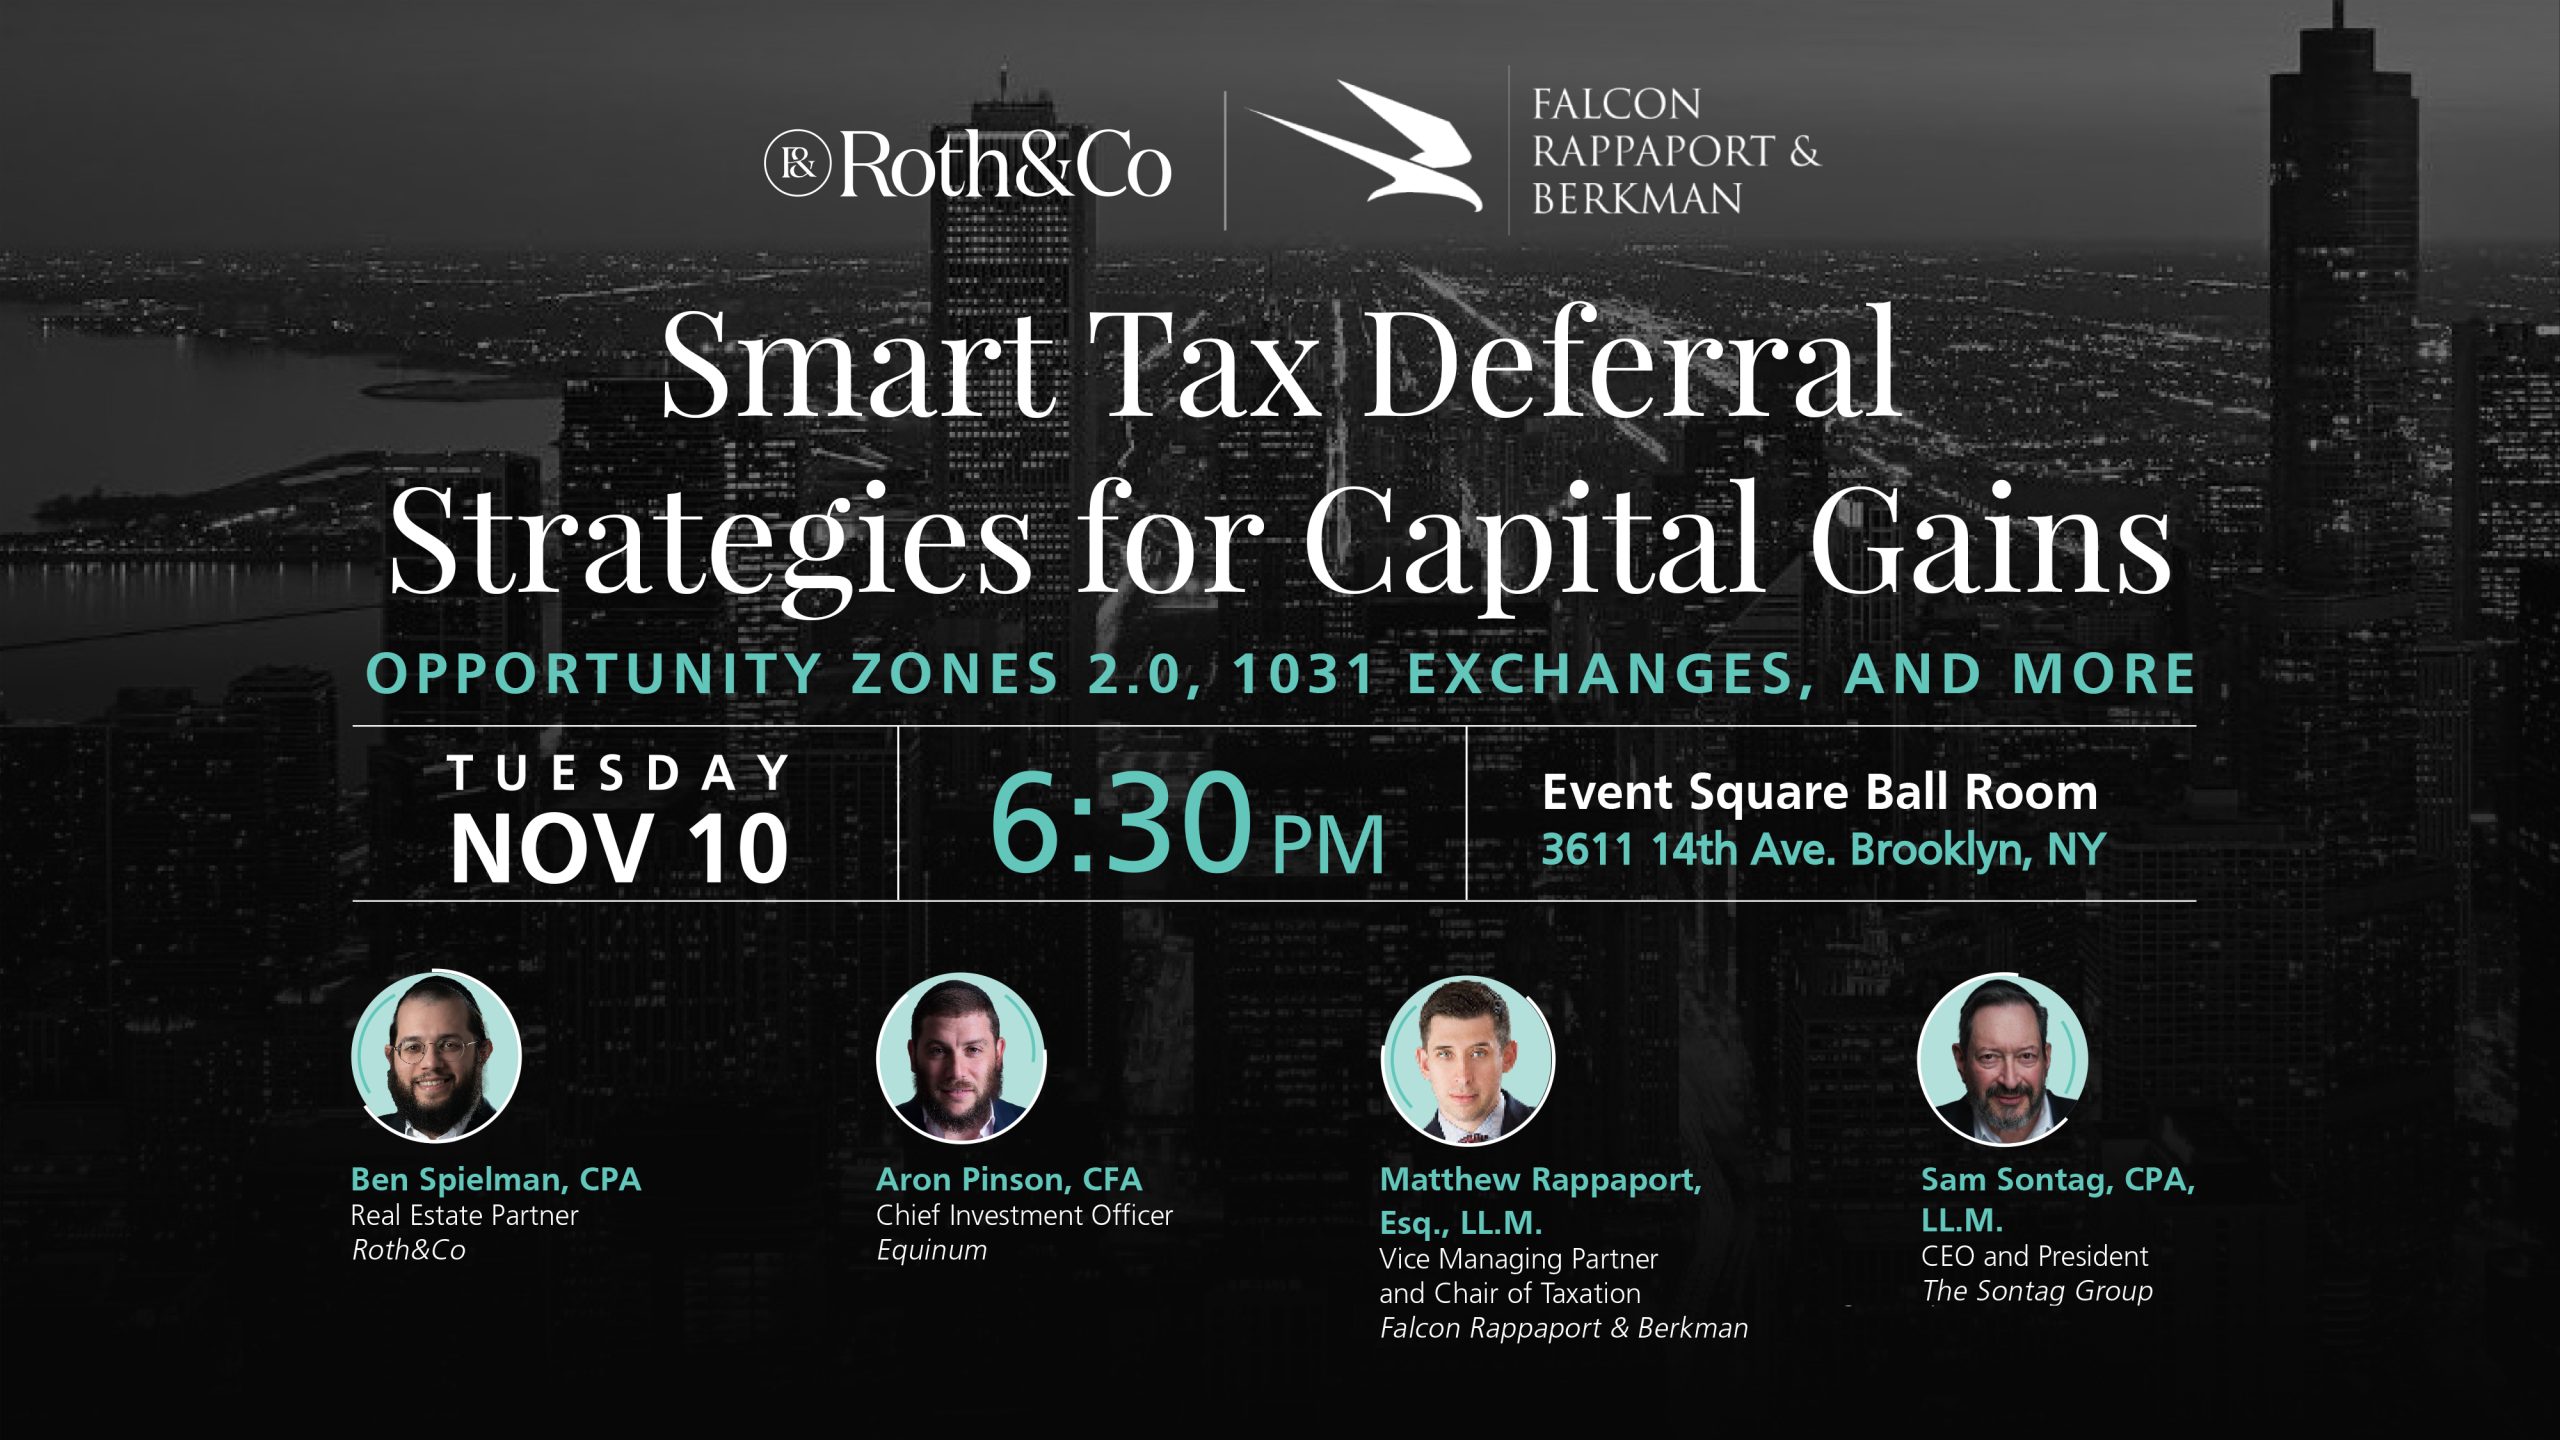
Four advisers addressed this topic at a November 10 event on tax deferral hosted by Roth&Co and Falcon Rappaport & Berkman LLP: Ben Spielman, CPA, a partner at Roth&Co; Sam Sontag, an attorney and CPA and president of The Sontag Group LLC; Matthew Rappaport, Esq., vice managing partner and chair of taxation at Falcon Rappaport & Berkman; and Aron Pinson, founder and CIO of Equinum Wealth Management, an affiliate of Roth&Co.
Is Less Tax Always the Goal?
The advisers began with a question many investors overlook: Is paying less tax always the goal? Not necessarily. The right strategy depends on an investor’s circumstances and what he or she wants the money to do. A plan that minimizes this year’s tax bill can still be the wrong one if it locks up capital or concentrates risk.
1031 Exchanges: Swapping Property, Deferring Tax
Sontag introduced the option of a 1031 exchange as one that lets an investor defer tax on the sale of investment property by rolling the proceeds into another property. Named for a section of the tax code, it has applied only to real property since the 2017 tax law. For investors who want to stay in real estate, the full proceeds of a sale can go into a new property of higher value.
Sontag described a common scenario: an owner whose property is heavily depreciated and has been refinanced many times, leaving a low tax basis, a large loan and a building worth less than the debt. If the loan is non-recourse, meaning the lender can look only to the property and not to the borrower personally, a 1031 is feasible.
With non-recourse debt, the relief of the loan is treated as sale proceeds even when the debt exceeds the property’s value, so an owner can face a taxable gain with no cash to pay it. A 1031 can defer that gain, provided the replacement property carries at least as much debt or the investor makes up the difference in cash. With a recourse loan, the portion of debt above the property’s value is generally treated as cancellation-of-debt income, if the relevant debt is actually forgiven. An underwater property alone does not create cancellation-of-debt income. It would be taxed at ordinary rates, which a 1031 cannot defer.
Investors are strongly advised to line up the replacement property before selling. The clock starts at closing. An investor has 45 calendar days to identify replacement properties in writing, and the deadline to close is the earlier of 180 days or the applicable tax-return deadline, including extensions. The two periods run at the same time rather than back-to-back. A standard approach is where a qualified intermediary holds the proceeds, and the seller cannot touch them. Miss either deadline and the sale becomes fully taxable. An investor who waits until day 44 to choose has just 136 days left to close, and one who has not yet shopped may be forced into a rushed decision.
Also worth noting is that members who are leaving a multi-member LLC need not move in lockstep. Owners of a multi-member LLC may have different reinvestment goals, but pursuing different strategies requires careful structuring. An LLC taxed as a partnership generally conducts a 1031 exchange at the entity level; individual members cannot exchange their partnership interests under Section 1031. Eligible gains passed through to members may instead qualify for individual Opportunity Zone elections.
Opportunity Zones: The Original Program and 2.0
A common misconception is that investing ordinary capital in an Opportunity Zone can earn benefit. This is incorrect. The process must begin with the sale of a capital asset to an unrelated party at a gain. That sale can also come from eligible gains that appear on a K-1. If the gain is $1 million, the investor matches that amount in a qualified opportunity fund within the prescribed time. The money can also go into an operating business in a zone, not only a real estate project.
The benefits include deferral of the gain, a reduction in the tax on it, and no tax on appreciation if the investment is held 10 years.
The “prescribed time” is generally 180 days from when the gain is recognized. For gains passed through on a K-1, partners can choose among three start dates: the sale date, the entity’s year-end or the due date of its tax return.
Timing is where the original program and its successor diverge. Under the original rules, deferred gain must be recognized on December 31, 2026, and investors who held five or seven years received a 10% or 15% reduction in that gain. Investors who put money in earlier must therefore plan for the tax coming due.
In 2025, the One Big Beautiful Bill Act made the program permanent. For investments made on or after January 1, 2027, deferral rolls for five years from each investment, followed by a single 10% basis increase, or 30% for qualified rural funds. The 10-year exclusion remains, with a 30-year cap, and new zone designations take effect January 1, 2027.
Can an investor roll an original-program investment into the new one? The IRS has addressed this and says ‘no’. Notice 2026-40, issued in June, confirms that gain recognized solely because of the December 31, 2026, date cannot be reinvested in a new fund.
For investors who prefer to stay out of development qualified opportunity funds are an option. They often hold multiple projects of different types, such as industrial and office, in different regions, which means lower return but lower risk.
Beyond Real Estate: Gifting and Loss Harvesting
Investors use two other strategies to limit tax exposure. The first applies to a business owner who expects to sell: gifting appreciated shares to charity before the sale. There are dual benefits to this move. The donor generally receives a deduction for the shares’ fair market value if they were held longer than a year, and because fewer shares are sold, the eventual gain is smaller. Deductions are subject to income-based limits.
The second is tax-loss harvesting: selling investments at a loss to offset gains elsewhere. It works best when a business sale is known well in advance and the investor has equity exposure.
To illustrate, consider the S&P 500, which has historically averaged roughly 10% a year, though rarely in any single year and never with a guarantee. Rather than owning one index fund, an investor can own a basket of the individual stocks that mimic the index, an approach often called direct indexing. Because each stock is owned separately, algorithms can sell those that have fallen, bank the losses and buy similar stocks, keeping returns close to the index even in a rising market. The wash-sale rule bars claiming a loss if the same or a substantially identical security is bought within 30 days before or after the sale, which is why the swaps are into similar holdings rather than identical ones.
Used alongside an Opportunity Zone investment, those losses can accumulate until the deferred gain is recognized, which under the new rules comes five years after investment, potentially offsetting it.
So, What Should You Do?
Facing a large gain, investors have different options. A 1031 exchange offers federal and state benefits and, for tax purposes, “kicks the can down the road.” An Opportunity Zone investment suits owners breaking up a partnership or S corporation, or those interested in development; held for 10 years, the appreciation is tax-free on exit. It is geographically limited, while a 1031 is not.
The common thread: match the tool to the circumstances and to your ultimate goal. Start early and respect the clocks.
This material has been prepared for informational purposes only, and is not intended to provide or be relied upon for legal or tax advice. If you have any specific legal or tax questions regarding this content or related issues, please consult with your professional legal or tax advisor.